

Mexico's Top 10 Mining Companies’ Revenue Exceeds MX$517B
 By Paloma Duran | Journalist and Industry Analyst -
Tue, 04/28/2026 - 16:48
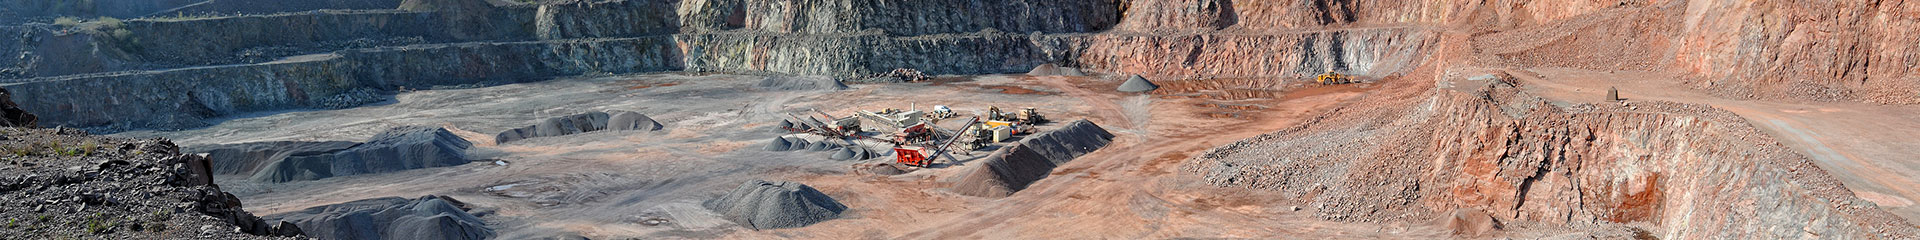
Ten companies account for the bulk of Mexico's mining output, with combined annual revenues exceeding MX$517 billion (US$29.74 billion), according to Expansión's ranking of the 500 most important companies in Mexico. The sector spans silver, gold, zinc and copper extraction, and remains one of the country's principal industries, generating a GDP of nearly MX$940.69 billion in 3Q25 from metallic and non-metallic mineral activity, excluding oil and gas.
Mexican Conglomerates Lead by Revenue
Americas Mining Corporation tops the ranking with revenues of MX$227.23 billion. The holding company, controlled by Germán Larrea Mota, consolidates copper, silver, molybdenum, zinc and gold operations across Mexico, Peru, the United States and Spain through subsidiaries including Southern Copper Corporation and Asarco LLC.
Industrias Peñoles ranks second with revenues of MX$121.9 billion and 15,613 employees. Founded in 1887 and listed on the Mexican Stock Exchange since 1968, the company is the world's largest refined silver producer and a leading producer of gold, lead and zinc. Fresnillo PLC, also part of Grupo BAL, follows with revenues of MX$64.09 billion and 7,179 employees. It operates six mines in Mexico, holds concessions covering around 2.1ha million and ranks as the world's largest primary silver producer.
Minera Frisco, part of Carlos Slim Helú's Grupo Carso, reported revenues of MX$10.46 billion and employs 3,142 people. The company produces lead-silver and zinc concentrates, copper cathodes and gold-silver doré bars.
North American Capital Drives Foreign Presence
The remaining six companies in the top ten are based in the United States and Canada, two countries that have historically financed and developed mining projects in Mexico. Between 1999 and 2024, the sector accumulated US$34.47 billion in FDI, with Canada as the leading source, followed by the United States.
Newmont Minera Peñasquito, the US-based miner operating in Zacatecas, reported revenues of MX$42.56 billion with 2,665 employees. The Peñasquito complex, one of the world's largest silver mines, produces gold, silver, lead and zinc from two open-pit operations.
Canada's Torex Gold Resources generated revenues of MX$20.45 billion with 1,200 employees, operating the Morelos mining complex across roughly 29,000ha in Guerrero. First Majestic Silver, also Canadian, posted revenues of MX$10.11 billion and employs 3,818 people across four underground mines in Mexico. Pan American Silver Corp. reported revenues of MX$7.15 billion and 2,720 employees, and in 2025 acquired MAG Silver Corp., gaining a combined 44% stake in the Juanicipio mine in Zacatecas.
US-based Coeur Mining Mexicana reported revenues of MX$6.95 billion with 869 employees, with the Palmarejo complex in Chihuahua contributing approximately 60% of its parent company's global silver output and about one-third of its gold production. Canadian producer Alamos Gold rounds out the top ten with revenues of MX$6.54 billion and 519 employees.
Sector Structure and Labor
As of May 2025, the sector comprised 2,886 registered economic units, most of them companies with between zero and 10 employees, reflecting an industry where large corporations coexist with small-scale operations. Mining activity is concentrated geographically, with Zacatecas, Sonora and Chihuahua accounting for the largest share of accumulated mining investment.
The sector employs approximately 265,000 people, 87.5% of them men. Women represent 12.5% of the workforce but earn a higher average monthly salary than their male counterparts. The average age of workers is 39, with most roles linked directly to mineral extraction and equipment operation.
Policy Barriers Temper Mexico's Mining Investment Rebound
Mexico climbed to 36th place in the Fraser Institute's 2025 Annual Survey of Mining Companies, up from 49th the previous year, as its score on the Investment Attractiveness Index rose by 13.25 points. The shift was driven largely by mineral potential, Mexico jumped from 27th to 7th globally on the Best Practices Mineral Potential Index, leading Latin America ahead of Brazil at 11th, Peru at 28th and Chile at 29th. That geological appeal is reflected in the operations of the sector's top players.
Policy performance, however, lags behind. Mexico ranked 53rd out of 68 on the Policy Perception Index, trailing regional peers including Chile at 24th and Brazil at 29th. All survey respondents for Mexico identified security and political stability as major deterrents to investment. "Changes in mining law that limit exploration, no new concessions, and changes in the national water law are deterrents to investment," said a producer company.
Since regulatory amendments introduced in May 2023, the sector has operated under tighter state supervision, extended permitting cycles and stalled concession grants. These conditions weigh most heavily on exploration-stage activity in states like Zacatecas, Sonora and Chihuahua, where foreign operators run some of their most productive assets.
Pablo Méndez, Managing Partner, EC Rubio, notes that many companies have responded by redirecting capital toward brownfield expansion at established mines rather than pursuing new deposits. Federal authorities have signaled a more pragmatic approach in 2026, including announcements on resuming geological exploration in Sonora, Durango and Sinaloa.
Laura Díaz, Partner, DBR Abogados, warns that compliance timelines remain misaligned with operational realities, citing the 60% water recycling mandate as a measure whose required infrastructure and permitting can take years to finalize. "Before investing, companies must clearly understand the legal status of the concession, existing permits, fiscal obligations, community relations, water rights, and environmental compliance," she advises.
You May Like




Most popular



