

MP Materials, USA Rare Earth Hit by China Export Controls
 By Paloma Duran | Journalist and Industry Analyst -
Wed, 06/24/2026 - 11:14
China's designation of MP Materials and USA Rare Earth on its export control list intensifies the US-China critical minerals confrontation, restricting access to dual-use technologies for the two firms anchoring Washington's mine-to-magnet supply chain strategy. For Mexico, the escalation compounds procurement risk for automotive and aerospace manufacturers exposed to Chinese-origin materials, while highlighting the urgency of legislative reform to unlock domestic rare earth exploration.
China has placed two of the United States' most important rare earth companies on its export control list, escalating the ongoing confrontation over critical mineral supply chains and dealing a direct blow to Washington's efforts to build production capacity outside Chinese control.
The designations of MP Materials and USA Rare Earth both central to the US mine-to-magnet strategy, underscore that Beijing retains significant leverage over materials essential to advanced manufacturing, defense, and the energy transition, even as Western nations pour billions into alternatives.
What Is at Stake
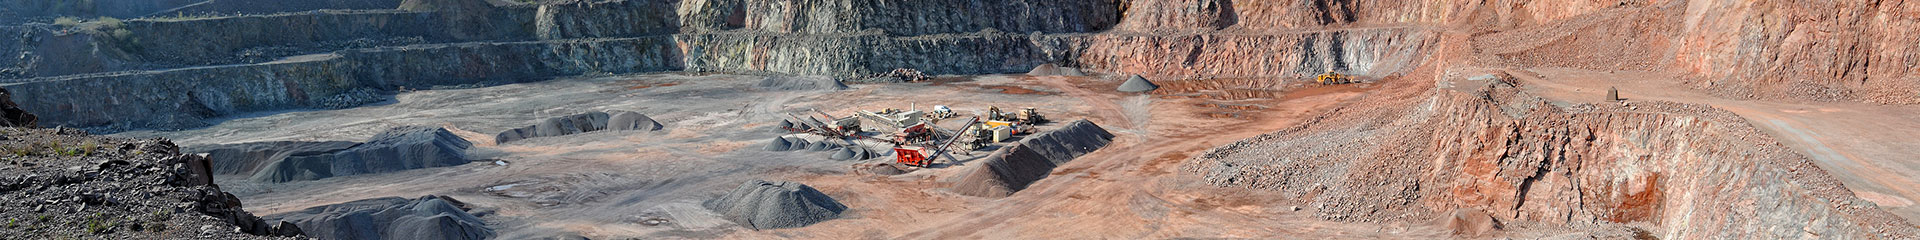
MP Materials operates the Mountain Pass facility in California, the only active rare earth mine in the United States, and counts the Pentagon as a shareholder. The Department of Defense has entered into a 10-year offtake agreement for the output of MP Materials' magnet manufacturing operations and established a minimum price floor of US$110/kg for its neodymium-praseodymium products. USA Rare Earth is advancing the Round Top mine in Texas, which is rich in heavy rare earth elements including dysprosium, and is developing a magnet manufacturing plant in Stillwater, Oklahoma, with a 5,000t annual capacity.
Both companies accelerated their development plans after China imposed export controls on key rare earth elements and magnets in April 2025, which led to shortages for US and European manufacturers and drove European rare earth prices to as much as six times domestic Chinese levels. China dominates approximately 60% of global rare earth mining and 91% of refining capacity, a concentration that gives Beijing structural leverage across defense, electric vehicle, semiconductor, and industrial motor supply chains.
The practical impact of the new designations on the two companies remains uncertain. Both have worked to localize supply chains and reduce exposure to Chinese inputs. However, many downstream industries continue to rely heavily on materials and processing technologies sourced from China, and the prohibition on third-country transfers adds a layer of extraterritorial risk for suppliers and partners globally.
G7 Context
The blacklisting came days after G7 nations agreed, at a June 17 summit in Paris, to cap rare earth imports from any single country outside the bloc and its partners at less than 60% by 2030. The measure targets China's supply dominance and is designed to create a structural floor for investment in alternative production. China controls approximately 91% of refined rare earth output, a share that has grown in recent years despite Western diversification efforts.
The timing of Beijing's response signals that diplomatic overtures between Washington and Beijing have not translated into a stable framework for critical mineral trade. The move follows a Trump state visit to Beijing in May 2026, where the two governments had sought to manage trade tensions. Chinese export restrictions paused under the October 2025 mutual stand-down with the US remain in effect until November 2026, after which a broader suite of measures could be reimposed.
Mexico's Position in the Supply Chain
The escalation carries direct implications for Mexico, which is navigating its own critical minerals strategy amid competing pressures from Washington and Beijing. Mexico ranks among the top global producers of eight minerals classified as critical by the US Geological Survey, including antimony, copper, fluorite, graphite, silver and zinc. Minister of Economy Marcelo Ebrard has identified 13 additional minerals, including rare earths, as strategic inputs Mexico needs to secure. The country's rare earth minerals market was valued at US$7.9 billion in 2025 and is projected to reach US$12.8 billion by 2031, driven by demand from the automotive, aerospace, and defense sectors.
During its 2026 pro tempore presidency of the Pacific Alliance, Mexico has made industrialization of critical minerals a central policy priority. "These resources are no longer just commodities but essential strategic assets for regional sovereignty," said Sergio Contreras, representing the Mexican Business Council for Foreign Trade and the Pacific Alliance Business Council. The bloc, comprising Chile, Colombia, Mexico, Peru, and Costa Rica, represents 40% of Latin America's GDP and is aligning its mining and processing sectors to support semiconductor and battery manufacturing.
However, Mexico faces structural constraints that limit how quickly it can convert geological endowment into production. Current mining legislation designates rare earth exploration as a state-exclusive activity, restricting private and foreign participation. Raúl García, President, College of Mining Engineers, Metallurgists, and Geologists of Mexico, has warned that without reform, "Mexico will be an importer of rare earth minerals," leaving its nearshoring competitiveness exposed to the same supply disruptions now affecting US manufacturers.
Mexico participated in the US-convened Inaugural Critical Minerals Ministerial on Feb. 4, 2026, which brought together 55 nations to formalize a preferential trade zone for strategic materials, and has engaged with Latin America, India, and Canada to secure supply of critical inputs.
For manufacturers operating in Mexico, particularly in automotive and aerospace, the US-China rare earth confrontation introduces a compounding procurement risk. China's rare earth export controls have already disrupted US and European manufacturers, and the extension of restrictions to third-country transfers means that Mexican operations with exposure to Chinese-origin materials or technologies could face secondary compliance obligations.


Most popular



