

Mustang Minerals Sells El Cobre Asset, Exits Mexico
 By Paloma Duran | Journalist and Industry Analyst -
Thu, 07/02/2026 - 09:01
Mustang Minerals' US$1.5 million sale of its El Cobre copper-gold project in Veracruz reflects a broader consolidation trend among junior miners exiting non-core Mexican assets amid tighter Federal Mining Law enforcement, including the cancellation of over 1,200 concessions in early 2026. The shift coincides with parallel government efforts to streamline permitting.
Mustang Minerals has agreed to sell its El Cobre copper-gold porphyry project in Mexico for US$1.5 million, a move the company says will let it concentrate entirely on its Nevada exploration portfolio. "With the sale of El Cobre, we are now entirely focused on our Nevada, USA copper and gold projects," J Duane Poliquin, Mustang's chairman, said. "The sale of El Cobre allows us to move forward with our 2026 exploration plans in the coming weeks."
Mustang has signed a share purchase agreement dated June 23 with Minerales Criticos De Mexico, S.A.P.I. De C.V. to sell all shares of Minera Alondra S.A. de C.V., the wholly owned Mexican subsidiary that holds El Cobre. The two companies are dealing at arm's length, and no finder's fee or commission applies to the transaction, which still requires regulatory approval, including sign-off from the TSX Venture Exchange.
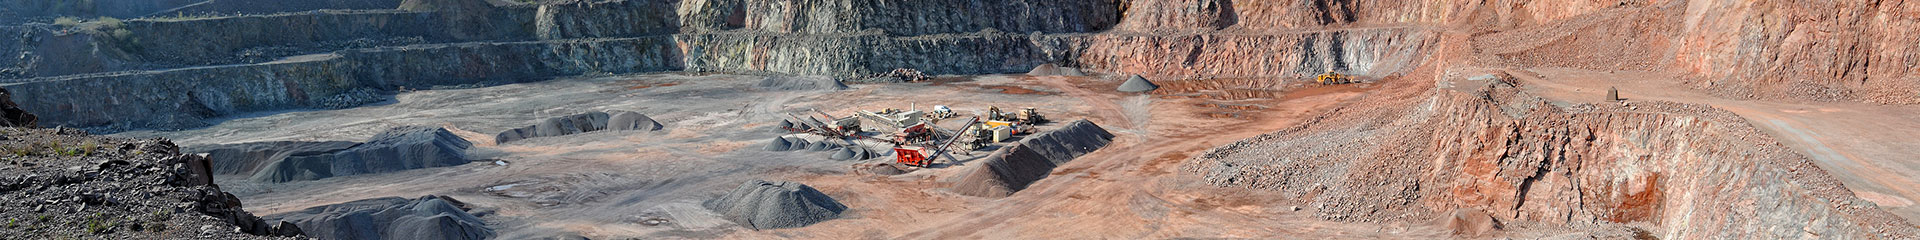
Located in Veracruz, El Cobre is no stranger to the exploration sector, having changed hands among junior miners for over a decade. The roughly 7,500ha claim block, positioned some 75km north of the port of Veracruz, has seen drill programs dating back to the early 2010s. Earlier work outlined copper-gold mineralization spanning more than four km of strike across four separate zones, Los Banos, El Porvenir, Norte and Villa Rica. The property's location near the Pan American Highway, the Laguna Verde nuclear facility and Mexico's power grid, along with reliable surface water at lower elevations, has traditionally been pitched as a logistical advantage.
The deposit's porphyry-style mineralization is tied to diorite intrusions cutting through intermediate volcanics, with earlier technical work drawing comparisons to Chile's Maricunga gold-copper belt. Historical drill results included a hole exceeding 100m at modest gold and roughly quarter-percent copper grades, though most of that drilling stayed shallow, leaving deeper potential largely untested. Notably, Poliquin previously chaired the company that held El Cobre before Mustang, giving him firsthand knowledge of the project he is now selling.
Once the El Cobre sale closes, Mustang's remaining holdings will consist of several central Nevada properties targeting copper-gold porphyry and high-sulphidation gold-silver-copper systems. Surface alteration at Red Ring and Confusion Hills points to high-sulphidation potential with possible gold enrichment, while exploration at Pilot is focused on copper-gold mineralization sitting beneath pyrophyllite-sericite alteration visible at surface.
Nevada has traditionally drawn North American exploration companies thanks to its well-established regulatory framework, comparatively efficient permitting, and decades of geological data accumulated by major operators in the state. Mustang said its 2026 exploration program for these properties is still being finalized, with details to follow, and Poliquin noted that completing the El Cobre divestment will let the company move that program forward within weeks.
A Mexican Mining Sector in Transition
Mustang's exit from Mexico comes as the country's mining industry shifts from an expansion-focused era to one defined by tighter enforcement and a renewed strategic push around critical minerals.
That strategic opening, however, has coincided with stricter domestic enforcement that has reshaped the calculus for junior exploration companies like Mustang. Reforms to the Federal Mining Law since 2022 cut concession terms, added public tenders and tightened reporting and environmental requirements; in February 2026 alone, authorities recovered more than 1,200 concessions covering nearly 890,000ha for non-compliance with fiscal or technical obligations, including 713 in protected natural areas. Industry voices have described the resulting environment as one where established, permitted producers with strong production and integrated environmental, social and governance strategies are best positioned to navigate volatility, while smaller or greenfield projects face longer permitting timelines and higher compliance risk.
Despite the tighter regulatory posture, authorities have also moved to streamline permitting in parallel, with a dedicated administrative unit working to clear backlogs and normalize processing timelines by mid-2026, an effort regulators describe as progress, even as the broader system remains far from fully cleared. State-level results illustrate the shift: in Zacatecas, one of the country's most active mining jurisdictions, officials say the local permit backlog dropped from 25 pending applications to just five within a single year, helping unlock a state investment pipeline now exceeding US$6.5 billion.
Capital, meanwhile, has continued flowing into Mexican mining overall. The country attracted a record US$40.9 billion in FDI in 2025, and analysts tracking the sector project up to US$7 billion more in mining-specific investment pending permit approvals, alongside roughly US$8.3 billion across 25 projects under development through 2029.
You May Like

Most popular



