

Sonoro Gold Updates Cerro Caliche’s PEA; Posts US$224 Million NPV
 By Fernando Mares | Journalist & Industry Analyst -
Mon, 03/09/2026 - 10:55
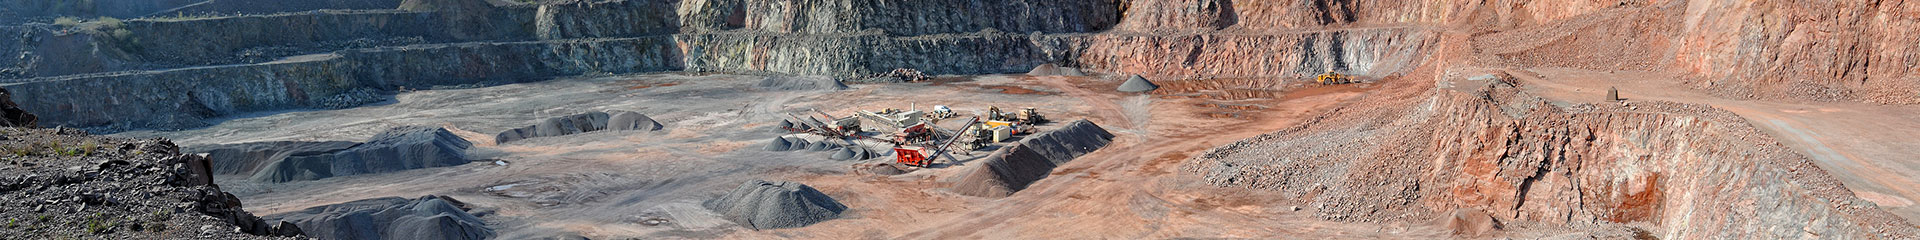
Sonoro Gold has released updated resource and economic assessments for its Cerro Caliche project in Sonora, reporting an after-tax NPV8 of US$224 million driven by elevated gold prices and a 10-year mine life. The company tripled its land position to 3,924 hectares through strategic acquisitions while advancing revised environmental and land-use permits with SEMARNAT to optimize its operational footprint. These developments, alongside a potential spin-out of the San Marcial asset, position the company to scale production capacity to 16,000t/d within Mexico’s competitive gold mining sector.
_______
Canada-based gold company Sonoro Gold announced the release of its updated Mineral Resource Estimate (MRE) and Preliminary Economic Assessment (PEA) for its Cerro Caliche gold project in Sonora. The company considers the updated reports better reflect the value of Cerro Caliche, which was driven up by higher gold prices and increased production rates.
Sonoro Gold noted that the studies were prepared by P&E Mining Consultants and evaluate a 10-year life of mine (LOM) open-pit, heap leach operation. The proposed plan initiates production at 12,000t/d for the first year before increasing to 16,000t/d for the remainder of the project's lifespan.
The PEA base case, calculated using US$3,500/oz gold and US$48/oz silver, reports an after-tax net present value discounted at 8% (NPV8) of US$224 million and an internal rate of return (IRR) of 50%. Under spot price assumptions of US$5,186/oz gold and US$88/oz silver, the after-tax NPV8 increases to US$525 million with a 91% IRR. Initial capital expenditure is estimated at US$83 million, which includes a US$11 million contingency, while sustaining capital costs are projected at US$26 million.
Cerro Caliche's operating profile anticipates a total production of 459,000 ounces of gold equivalent (AuEq) over the ten years, with an annual average production of 46,000oz AuEq. Cash operating costs are estimated at US$1,842/oz AuEq, while the all-in-sustaining costs (AISC) are projected at US$1,902/oz AuEq. Gold and silver recovery rates are modeled at 72% and 27%, respectively, with a calculated payback period of 1.7 years.
The updated MRA utilized a three-dimensional block model and drill hole assay results to define steeply dipping mineralized zones, generally within 125m of the surface.
Kenneth MacLeod, President and CEO, Sonoro Gold, stated that the revised mine plan and higher metal prices have increased the project's value. “With less than 30% of the known mineralized zones at the original Cerro Caliche concession drilled and assayed to date and the recent near-tripling of the concession size to the north and south, the potential for future expansion of the proposed mine, both in capacity and LOM, are considered to be favourable,” he noted.
Sonoro Gold Expands Cerro Caliche
Cerro Caliche is among the 83 active projects the government of Sonora monitors, and is one of the main gold projects in the country along with Torex Gold’s Media Luna expansion, Endeavour Silver’s Terronera mine, and GoGold Silver and Gold’s Los Ricos, as noted in the CAMIMEX Annual Report 2025.
Following an expansion in late 2025 and early 2026, Sonoro Gold has consolidated 3,924.26ha across 25 contiguous mining concessions, tripling its previous mineral land position. The company secured 100% control of the project by finalizing the US$5.18 million acquisition of the original 15 concession titles on Oct. 30, 2025. This was followed by the acquisition of 10 additional concessions from local residents for US$4 million, paid over four years, which extended known mineralized corridors to the northwest and southeast. To support this growth, Sonoro Gold raised over CA$6.1 million (US$4.3 million) through private placements in late 2025.
On the permitting front, Sonoro received TSXV acceptance for a surface rights lease agreement covering 3,908ha for an initial term of 12.5 years, with an option to extend to 25 years. The first-year financial obligations were satisfied with a US$3.1 million cash payment and the issuance of 5 million common shares. A revised Environmental Impact Assessment (EIA) was submitted to SEMARNAT in February 2025 to optimize the project footprint, and the company anticipates filing its Change of Land Use (CUS) permit by the end of 2025.
Sonoro Evaluates a San Marcial Project Spin-Out
Sonoro Gold has also been evaluating a reorganization to spin out its 100%-owned San Marcial gold-silver project into a wholly-owned subsidiary, Oronos Gold Corp. The company stated this move could unlock the value of the asset without diluting Sonoro Gold shareholders. The potential spin-out would be subject to shareholder approval, court approval, and TSXV listing requirements. A final decision is pending an independent valuation and tax review.
The company is proceeding cautiously, stating that spinning out an asset is a timely and costly process. No formal reorganization will be announced until the board has reviewed an independent valuation of San Marcial and confirmed all potential tax liabilities, as reported by MBN. To satisfy TSXV listing requirements, Oronos Gold would need to demonstrate CA$100,000 in prior exploration expenses, have CA$200,000 for a new exploration program, and hold another CA$100,000 in unallocated working capital, which would likely be funded by a private placement, according to Sonoro Gold.
You May Like


Most popular



