

BP Markets Stakes in Two US Gulf Megaprojects
BP’s decision to divest minority stakes in its multi-billion-dollar Kaskida and Tiber ultra-deepwater projects under new CEO Meg O'Neill marks a strategic shift to recycle capital and share risks within core oil and gas developments. This portfolio optimization provides a critical benchmark for Mexico's nascent deepwater horizon, emphasizing the extreme capital discipline global majors enforce even during high-price environments. While validating the geological potential of the shared Paleogene formation, BP’s cautious sell-down highlights the operational and financing headwinds cash-strapped PEMEX faces as it attempts to advance its standalone Trion deepwater partnership amid severe domestic budget cuts.
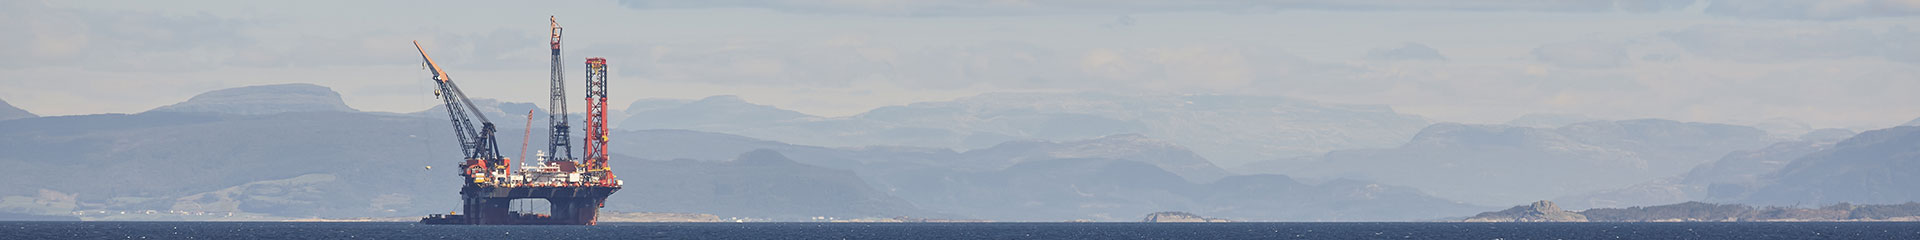
BP has begun the process of selling minority stakes in two major Gulf of Mexico oil projects, Kaskida and Tiber, as the British energy company seeks partners for some of its most important upstream developments in the United States. The size of the stakes being offered has not been disclosed, but BP had reportedly considered selling up to 50% in each project.
The operation could represent billions of dollars and forms part of the strategy driven by BP's new CEO, Meg O'Neill, the first external leader to take the helm of BP in more than a century of history, who took office in April. While Kaskida and Tiber sit on the US side of the Gulf, the sale process, and the strategic logic behind it, carries direct relevance for how Mexico's own deepwater program, and PEMEX's relationships with international operators, are likely to evolve over the same horizon.
Kaskida and Tiber are among BP's most significant offshore developments in the US Gulf of Mexico. Each project is expected to have the capacity to produce up to 80Mb/d once operational. BP approved Kaskida in 2024, marking its sixth operated production hub in the region, with first production expected in 2029 and a floating production platform tied to subsea wells in its first development phase. The company approved the Tiber-Guadalupe project in 2025, fully owned by BP, which is expected to become its seventh operated hub in the Gulf, with first production planned for 2030. Together, the projects are part of BP's effort to unlock resources in the Paleogene formation, a deepwater oil-rich area of the Gulf.
The Kaskida field has estimated oil in place of approximately 3 billion barrels, located in the Keathley Canyon block of the US Gulf, discovered in 2006 at a water depth of approximately 1,790m, depths comparable to those found across the maritime boundary in Mexico's Perdido Fold Belt.
A Strategic Reversal at BP
The sale process comes after BP modified its corporate strategy to refocus on oil and gas, reducing the emphasis it had placed on renewable energy in recent years, a shift driven by investor pressure and stock performance that had fallen short of expectations. The company has faced sustained investor pressure to improve returns and strengthen its upstream portfolio, making the Gulf of Mexico a key pillar of its long-term production plans.
BP considers the US market one of the primary engines of its future expansion, with a target to raise US production to approximately one million barrels of oil equivalent per day by 2030, a significant share of its global production target. Selling minority stakes in Kaskida and Tiber while retaining operatorship is a capital-recycling strategy: it brings in partner capital to fund development while preserving BP's control over execution, the same structure international majors have used in Mexico's mixed contract and farm-out frameworks.
The Mexican Deepwater Mirror
The US Gulf and the Mexican Gulf share the same geology across the maritime boundary: the Perdido Fold Belt and the broader Paleogene formation extend on both sides. Mexican deepwater remains largely unexplored compared to the US Gulf; until 2016, cash-strapped PEMEX was the sole company involved in deepwater exploration on the Mexican side. Despite that lack of investment, exploratory drilling in the Perdido Fold Belt has corroborated the presence of significant hydrocarbon volumes of a quality similar to those found on the US side of the maritime border.
While the American Gulf saw production peak above 2MMb/d in pre-pandemic 2019, Mexico has yet to produce a single barrel of oil from deepwater plays, a gap that persists even as BP, Shell, Chevron, and other majors have built multi-hub deepwater portfolios just kilometers away on the US side.
Mexico's first ultra-deepwater development, Trion, discovered by PEMEX in 2012 and developed in partnership with Woodside following CNH approval, is expected to produce oil and gas by 2028, with peak output projected at 110Mb/d of oil and 101MMcf/d of gas. Trion remains, sixteen years after discovery, Mexico's only deepwater project with a credible path to first production, a single project compared to BP's seven operated hubs across the border.
BP is not a newcomer to Mexican waters. In partnership with Equinor and TotalEnergies, BP holds two deepwater blocks (1 and 3) in the Southeast Saline Basin, and is also a partner in shallow water block 34 in the same basin. Those holdings have remained largely in exploration and appraisal phases.
You May Like



Most popular



