

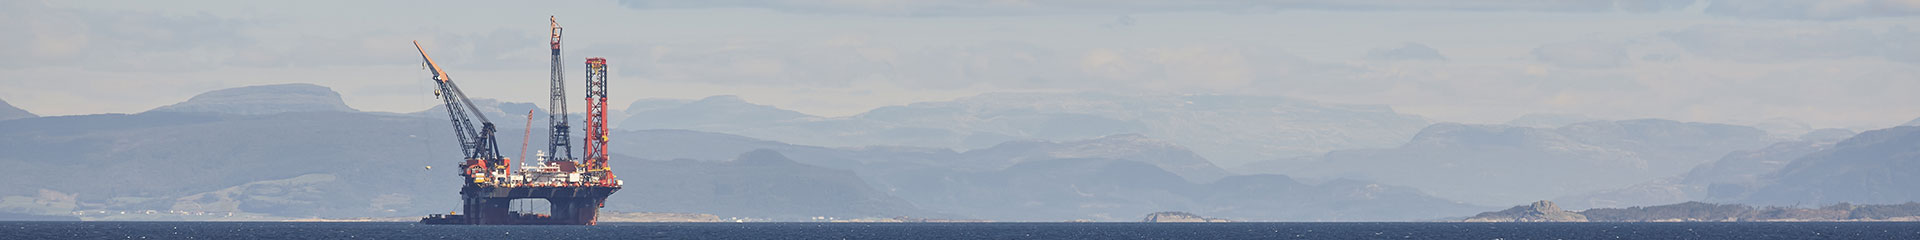
Shell Exits Na Kika and Coulomb in US$1.7 Billion Gulf Deal
Shell Offshore has agreed to sell its 50% non-operated working interest in the Gulf of Mexico's Na Kika platform and associated fields, alongside its 100% interest in the Coulomb subsea tieback, for US$1.7 billion. The asset package will be split equally between subsidiaries of Talos Energy and Ridgewood Energy Corporation for US$850 million each. While the deal allows Shell to rationalize mature, non-operated assets and reallocate capital toward higher-return operated projects, it expands the portfolio of independents like Talos by adding roughly 16Mboe/d of production. However, a structural caveat remains: BP holds a 30-day preferential purchase right over the Na Kika platform interests, which could block Talos and Ridgewood from the main hub if exercised.
Shell Offshore, a subsidiary of Shell, agreed on June 30 to sell its 50% non-operated working interest in the Na Kika platform and associated fields in the Gulf of Mexico, as well as its 100%-owned Coulomb subsea tieback, for a total consideration of US$1.7 billion. The assets will be acquired by subsidiaries of Talos Energy and Ridgewood Energy Corporation, with each buyer taking a 50% stake in the combined package.
Talos Energy will acquire a 25% non-operated working interest in the BP-operated Na Kika platform and the Kepler, Ariel, Fourier, and Herschel fields, along with a 50% working interest and operatorship in the Coulomb field, for net cash consideration of US$850 million. Ridgewood Energy will acquire the remaining 25% non-operated interest in the Na Kika assets.
Peter Costello, Shell's Upstream President, stated: "The Gulf of America is one of our highest-value basins, and we are actively shaping our portfolio to ensure our Upstream business continues to be resilient and increasingly competitive." The Na Kika semisubmersible platform, located in the Mississippi Canyon area, has served as a major production hub since first oil in November 2003. Developed originally as a 50/50 joint venture between BP and Shell, it was one of the earliest and most technically ambitious deepwater projects of its era, often described for its "octopus-like" layout of subsea tiebacks feeding a central floating production host.
The transaction is part of a broader industry trend of majors rationalizing mature or non-core positions in the Gulf of Mexico while independents like Talos consolidate scale and optimize infrastructure-heavy assets.
The Economics of the Transaction
Average 1Q26 production attributable to the interests Talos expects to acquire was approximately 16Mboe/d, of which approximately 77% was oil. The acquisition will add approximately 23MMboe of proved reserves and 10MMb of probable reserves, net to Talos.
Based on estimated interim cash flow from the assets since the July 1, 2025 effective date, Talos expects its final net cash consideration to be approximately US$450 million to US$500 million after interim cash flows. The transaction also includes a 50% upside-sharing agreement through the end of 2027, subject to commodity price thresholds and other conditions, specifically, the arrangement applies if realized oil prices exceed US$60/b.
Talos expects to finance the acquisition through a combination of cash on hand and debt, having secured US$150 million of incremental commitments from its existing lenders, increasing its borrowing base to US$850 million from US$700 million upon closing.
One structural risk: the Na Kika interests are subject to BP's 30-day preferential purchase right. If exercised, Talos said it would acquire only the 50% working interest and operatorship in the Coulomb field. BP already operates Na Kika with a 50% stake, if it exercises its preferential right over Shell's departing 50%, it would become sole owner of the platform, consolidating its position and removing Talos from the Na Kika equation entirely while still leaving Talos with the Coulomb operatorship.
Shell's Strategic Reorientation: Portfolio Discipline at Scale
The Na Kika sale is not an isolated transaction. Shell has been accelerating upstream portfolio rationalization throughout 2026, selling non-operated positions in mature assets and concentrating capital on higher-return operated developments. Shell will retain rights to offtake production from Na Kika and Coulomb through negotiated agreements with the buyers, and will receive uncapped upside-linked payments through 2027 and overriding royalty interests on production from future Na Kika tiebacks. That combination, divesting the equity stake while retaining commercial exposure through offtake and royalties, is the financial structure of a company managing capital intensity without abandoning commodity exposure in a basin it considers strategically important.
The Na Kika deal echoes BP's separate announcement that it is marketing minority stakes in its own Gulf flagship developments, Kaskida and Tiber, which carry individual peak production targets of 80Mb/d each. Together, the Shell and BP portfolio moves, both occurring within the same month, paint a consistent picture: majors in the Gulf of America are reducing equity in mature and non-operated positions while maintaining commercial access, freeing balance sheet capacity for their own higher-return operated developments and returning capital through asset sales rather than equity issuance.
You May Like



Most popular



